
As digital financial ecosystems evolve, customers increasingly expect access to a wide variety of financial products within a single platform. Fixed Deposits (FDs), traditionally offered through individual banks or NBFCs, are now being distributed through fintech apps, wealth platforms, and digital marketplaces that aggregate products from multiple financial institutions. This shift has created a new infrastructure challenge. Digital platforms want to offer FD products from multiple banks and NBFCs, but managing different deposit products, interest structures, tenures, and operational workflows across multiple partners can quickly become complex. Finspring addresses this challenge through its multi-partner FD enablement infrastructure. By providing a standardized platform that connects multiple financial institutions and distribution platforms, Finspring enables digital ecosystems to manage diverse FD products efficiently.
This article explores how Finspring supports multi-partner FD enablement, allowing financial platforms to offer a broad range of FD products while maintaining operational simplicity, regulatory alignment, and a seamless user experience.
The Rise of Multi-Institution FD Marketplaces
Historically, fixed deposits were distributed directly by the issuing institution. Customers typically opened deposits through a specific bank branch or through that bank’s digital interface.
Today, the financial landscape is shifting toward aggregated financial marketplaces. Fintech platforms and wealth apps increasingly provide access to deposit products from multiple institutions.
This approach offers several benefits for both platforms and users.
Benefits for Digital Platforms
- Access to a wider range of deposit products
- Increased customer engagement through product choice
- Improved competitiveness with diversified offerings
- Higher transaction volumes and distribution potential
Benefits for Customers
- Ability to compare interest rates across institutions
- Greater flexibility in choosing deposit tenures
- Access to multiple trusted financial institutions within a single app
However, managing FD products from multiple partners introduces operational complexity that requires specialized infrastructure.
The Challenge of Product Diversity in FD Distribution
Each bank or NBFC offering fixed deposits may structure their products differently. These variations create challenges for digital platforms attempting to aggregate FD products.
Common differences across institutions include:
- interest rate structures
- tenure options
- minimum deposit requirements
- payout schedules
- renewal policies
- operational workflows
Without a standardized framework, integrating these variations can lead to complicated engineering work and inconsistent user experiences.
This is where multi-partner FD enablement infrastructure becomes critical.
Finspring’s Approach to Multi-Partner FD Enablement
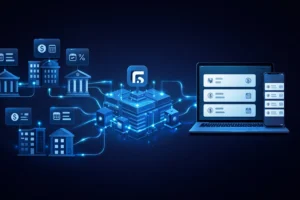
Finspring’s platform is designed to simplify the management of FD products across multiple financial institutions. Instead of requiring platforms to build separate integrations for each partner, Finspring provides a unified infrastructure layer that standardizes how FD products are discovered, booked, and managed.
Through this approach, digital platforms can access multiple deposit providers through a single integration.
This dramatically reduces the complexity associated with managing product diversity across financial institutions.
Standardized Product Framework
One of the most important components of Finspring’s infrastructure is its standardized product framework.
Although different banks and NBFCs structure their FD products differently, Finspring converts these variations into a standardized data structure.
This structure organizes deposit attributes such as:
- interest rates
- tenure durations
- investment thresholds
- payout schedules
- maturity details
By normalizing product information, Finspring allows digital platforms to present FD products in a consistent format.
This standardization improves both developer efficiency and user experience.
Dynamic Product Discovery
Product discovery plays an important role in helping users explore available FD options across institutions.
Finspring enables digital platforms to retrieve available FD offerings dynamically through APIs. This allows platforms to display multiple deposit products in real time.
Users can compare FD options across institutions based on key factors such as:
- interest rates
- tenure length
- payout type
- investment requirements
Dynamic product discovery ensures that users always see the most accurate and up-to-date deposit offerings available through the platform.
Unified Deposit Booking Workflow
One of the biggest challenges in multi-partner FD distribution is managing the booking process across different institutions.
Each bank or NBFC may have unique operational workflows for deposit creation and confirmation.
Finspring solves this problem by providing a unified booking workflow that standardizes deposit transactions across partners.
The booking workflow includes:
- validating deposit parameters
- confirming payment completion
- creating deposit records
- synchronizing data with partner institutions
This standardized process allows platforms to manage deposits across multiple partners without implementing separate booking systems.
Lifecycle Management Across Multiple Institutions
After a deposit is booked, the system must track its lifecycle from creation to maturity.
When FD products come from multiple institutions, lifecycle management becomes even more complex.
Finspring’s infrastructure manages lifecycle events consistently across all partner institutions.
Lifecycle tracking includes:
- deposit creation
- interest accrual
- tenure progression
- maturity tracking
- payout processing
By centralizing lifecycle management, Finspring ensures that deposit data remains consistent across platforms and partner institutions.
Managing Product Updates and Rate Changes
Interest rates and deposit product parameters often change based on market conditions or institutional policies.
Without centralized infrastructure, updating these changes across multiple platforms can become difficult.
Finspring’s system enables financial institutions to update product attributes directly within the platform.
These updates are automatically reflected across connected distribution platforms, ensuring that users always see accurate deposit offerings.
This capability simplifies product management while reducing operational overhead.
Compliance Across Multiple Partners
Regulatory compliance becomes more complex when deposits are distributed across multiple financial institutions.
Each partner institution must ensure that deposit transactions meet compliance standards related to customer verification, transaction monitoring, and reporting.
Finspring embeds compliance mechanisms into its infrastructure to ensure that deposits distributed through the platform meet regulatory requirements.
These mechanisms include:
- onboarding verification workflows
- transaction monitoring
- audit trail logging
- reporting infrastructure
By integrating compliance checks into the platform, Finspring ensures that multi-partner deposit distribution remains aligned with regulatory expectations.
Operational Visibility for Distribution Platforms
Managing FD products from multiple partners requires strong operational oversight.
Finspring provides reporting dashboards that give platforms visibility into their deposit operations.
These dashboards provide insights such as:
- deposits booked across institutions
- distribution performance by partner
- upcoming maturity schedules
- portfolio summaries
Operational visibility allows platforms to manage large-scale deposit distribution effectively.
Strategic Benefits of Multi-Partner FD Enablement
Finspring’s infrastructure enables digital platforms to manage diverse deposit offerings while maintaining operational efficiency.
Key benefits include:
Expanded Product Offerings
Platforms can offer FD products from multiple banks and NBFCs through a single integration.
Simplified Integration
Unified APIs eliminate the need for multiple custom integrations.
Consistent User Experience
Standardized product structures ensure that users can easily compare deposit options.
Scalable Distribution
Platforms can add new financial partners without redesigning their infrastructure.
The Future of Aggregated Financial Products
The financial services industry is moving toward ecosystems where multiple financial institutions collaborate through digital platforms to distribute products.
In this environment, infrastructure capable of supporting multi-partner financial products becomes essential.
Finspring’s multi-partner FD enablement platform represents a key step toward this future. By standardizing deposit infrastructure and simplifying product integration, the platform enables financial institutions and digital platforms to collaborate more efficiently.
As digital finance continues to expand, the ability to manage diverse financial products across multiple partners will become increasingly important.
Conclusion
Offering fixed deposit products from multiple banks and NBFCs can significantly enhance the value proposition of digital financial platforms. However, managing product diversity across institutions introduces technical and operational complexity.
Finspring addresses this challenge through its multi-partner FD enablement infrastructure. By providing standardized product frameworks, unified booking workflows, centralized lifecycle management, and integrated compliance monitoring, the platform allows digital ecosystems to manage diverse FD offerings efficiently.
This infrastructure enables financial platforms to expand their product catalogs while maintaining operational simplicity and regulatory alignment.
In a financial ecosystem increasingly defined by collaboration and digital distribution, multi-partner FD enablement plays a crucial role in connecting financial institutions with modern digital platforms and expanding access to trusted savings products.



