
How Banks Are Rethinking Fixed Deposit Growth in a Platform-Driven World
For decades, fixed deposit distribution followed a predictable model. Banks owned the customer, controlled the channel, and pushed deposits through branches, relationship managers, and proprietary digital platforms.
That model is now under pressure.
Rising distribution costs, limited geographic reach, and changing customer behavior are forcing banks to rethink how fixed deposits are sold. The result is a clear industry shift: from bank-centric FD distribution to network-led distribution powered by aggregators.
This article breaks down why this transition is happening, how aggregator-led models work, and what banks can learn from a proven FD aggregation playbook.
Understanding the Bank-Centric FD Distribution Model
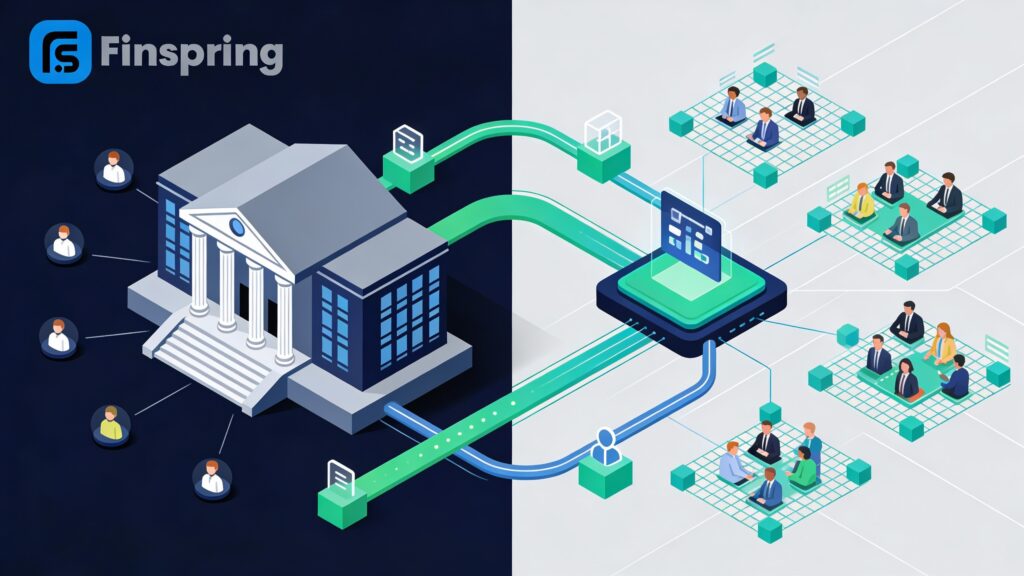
In a bank-centric model, the bank controls every layer of distribution:
- Customer acquisition
- Sales execution
- Technology
- Operations
- Servicing
Strengths of the Traditional Model
- Full control over customer experience
- Direct brand ownership
- Clear governance structure
Structural Limitations
- High fixed costs
- Linear scaling with headcount
- Slow market expansion
- Limited reach beyond core geographies
| Aspect | Bank-Centric Model |
|---|---|
| Cost structure | High fixed costs |
| Speed to market | Slow |
| Geographic reach | Limited |
| Scalability | Linear |
As competition for deposits intensifies, these limitations become more visible.
What Network-Led FD Distribution Looks Like
Network-led distribution flips the model.
Instead of banks building and managing every distribution node, they connect to existing networks of agents, advisors, and wealth managers through aggregator platforms.
In this model:
- Banks focus on products and risk
- Aggregators manage distribution infrastructure
- Agents bring customers and trust
The result is a modular, scalable FD ecosystem.
Why Banks Are Moving Toward Network-Led Models
1. Distribution Is No Longer a Competitive Advantage
In today’s market, distribution is infrastructure, not differentiation.
Banks win on:
- Product structuring
- Risk management
- Pricing discipline
Aggregator platforms allow banks to outsource distribution mechanics without giving up strategic control.
2. Customer Trust Lives With Advisors, Not Institutions
For fixed deposits, trust is critical.
Many customers still rely on:
- Local financial advisors
- Relationship managers
- Long-term agents
Network-led distribution allows banks to tap into this trust instead of trying to recreate it digitally or through branches.
3. Faster Reach Without Capital Expansion
Opening branches or hiring sales teams is capital-intensive.
Aggregator-led networks offer:
- Instant geographic expansion
- Access to niche customer segments
- Faster testing of new FD offerings
All without long setup cycles.
The Aggregator Playbook for Network-Led FD Distribution
Step 1: Decouple Distribution From Core Banking
The first shift is conceptual.
Banks must separate:
- Product ownership
- Risk control
- Compliance
from:
- Customer sourcing
- Agent enablement
- Distribution workflows
This decoupling makes external distribution possible.
Step 2: Standardize FD Products for Platform Distribution
Aggregator platforms work best when FD products are:
- Clearly parameterized
- API-enabled
- Rule-driven
| Product Element | Platform Requirement |
|---|---|
| Tenure | Configurable |
| Rates | Real-time |
| Eligibility | Rule-based |
| Documentation | Standardized |
Standardization allows products to scale across networks without friction.
Step 3: Enable Single-Platform Multi-Bank Access
From an agent’s perspective, simplicity matters.
Aggregator platforms provide:
- One dashboard
- Multiple banks
- Unified workflows
This increases agent adoption and ensures banks are visible where decisions are made.
Step 4: Maintain Control Through Rules, Not Presence
In a network-led model, control is enforced through:
- Automated validations
- Mandatory disclosures
- Audit logs
- Real-time reporting
Banks no longer need physical presence to maintain governance.
Step 5: Measure Performance at the Network Level
Network-led distribution produces richer data.
Banks can track:
- Agent-level performance
- Conversion rates by segment
- Fixed deposit rate sensitivity
- Regional demand patterns
This feedback loop helps refine products and pricing faster.
Bank-Centric vs Network-Led FD Distribution
| Dimension | Bank-Centric | Network-Led |
|---|---|---|
| Control | Direct | Rule-based |
| Cost | High fixed | Variable |
| Reach | Limited | Nationwide |
| Speed | Slow | Fast |
| Scalability | Linear | Exponential |
The network-led model does not replace banks. It amplifies them.
Addressing Common Bank Concerns
Loss of Brand Visibility
Aggregator platforms preserve bank branding at the point of sale while expanding reach.
Compliance Risk
Modern platforms embed compliance directly into workflows, often improving adherence.
Channel Conflict
Network-led distribution complements, rather than replaces, existing channels by serving incremental demand.
Why Aggregators Are Becoming Strategic Infrastructure
FD aggregators are evolving from intermediaries to infrastructure partners.
They provide:
- Technology
- Distribution access
- Data intelligence
- Operational leverage
Banks that treat aggregators as short-term channels often underutilize their value.
How Finspring Enables the Network-Led Model
Finspring.ai is designed to support the shift from bank-centric to network-led FD distribution by:
- Connecting banks to a broad agent ecosystem
- Enabling standardized, API-driven FD products
- Offering centralized control and reporting
- Supporting scalable, low-cost growth
This allows banks to expand fixed deposit reach without expanding operational complexity.
The Long-Term Strategic Impact
Network-led FD distribution changes how banks think about growth.
It enables:
- Faster liability scaling
- Lower customer acquisition costs
- Better product-market alignment
- Sustainable expansion across cycles
Over time, banks that embrace this model gain structural advantages over those that rely solely on owned channels.
Conclusion
The future of fixed deposit distribution is not owned by a single institution. It is built on networks.
By moving from a bank-centric mindset to a network-led approach, banks can scale FD growth faster, cheaper, and more flexibly. Aggregator platforms provide the playbook and the infrastructure to make this transition work.
For banks navigating competitive deposit markets, the question is no longer whether to adopt network-led distribution, but how quickly.
Read how banks achieve Low-CAC FD Growth, here.



